Is It Cheaper to Buy or Rent in Wyoming in 2026?
A Park County rent-vs.-buy comparison using actual local rental properties
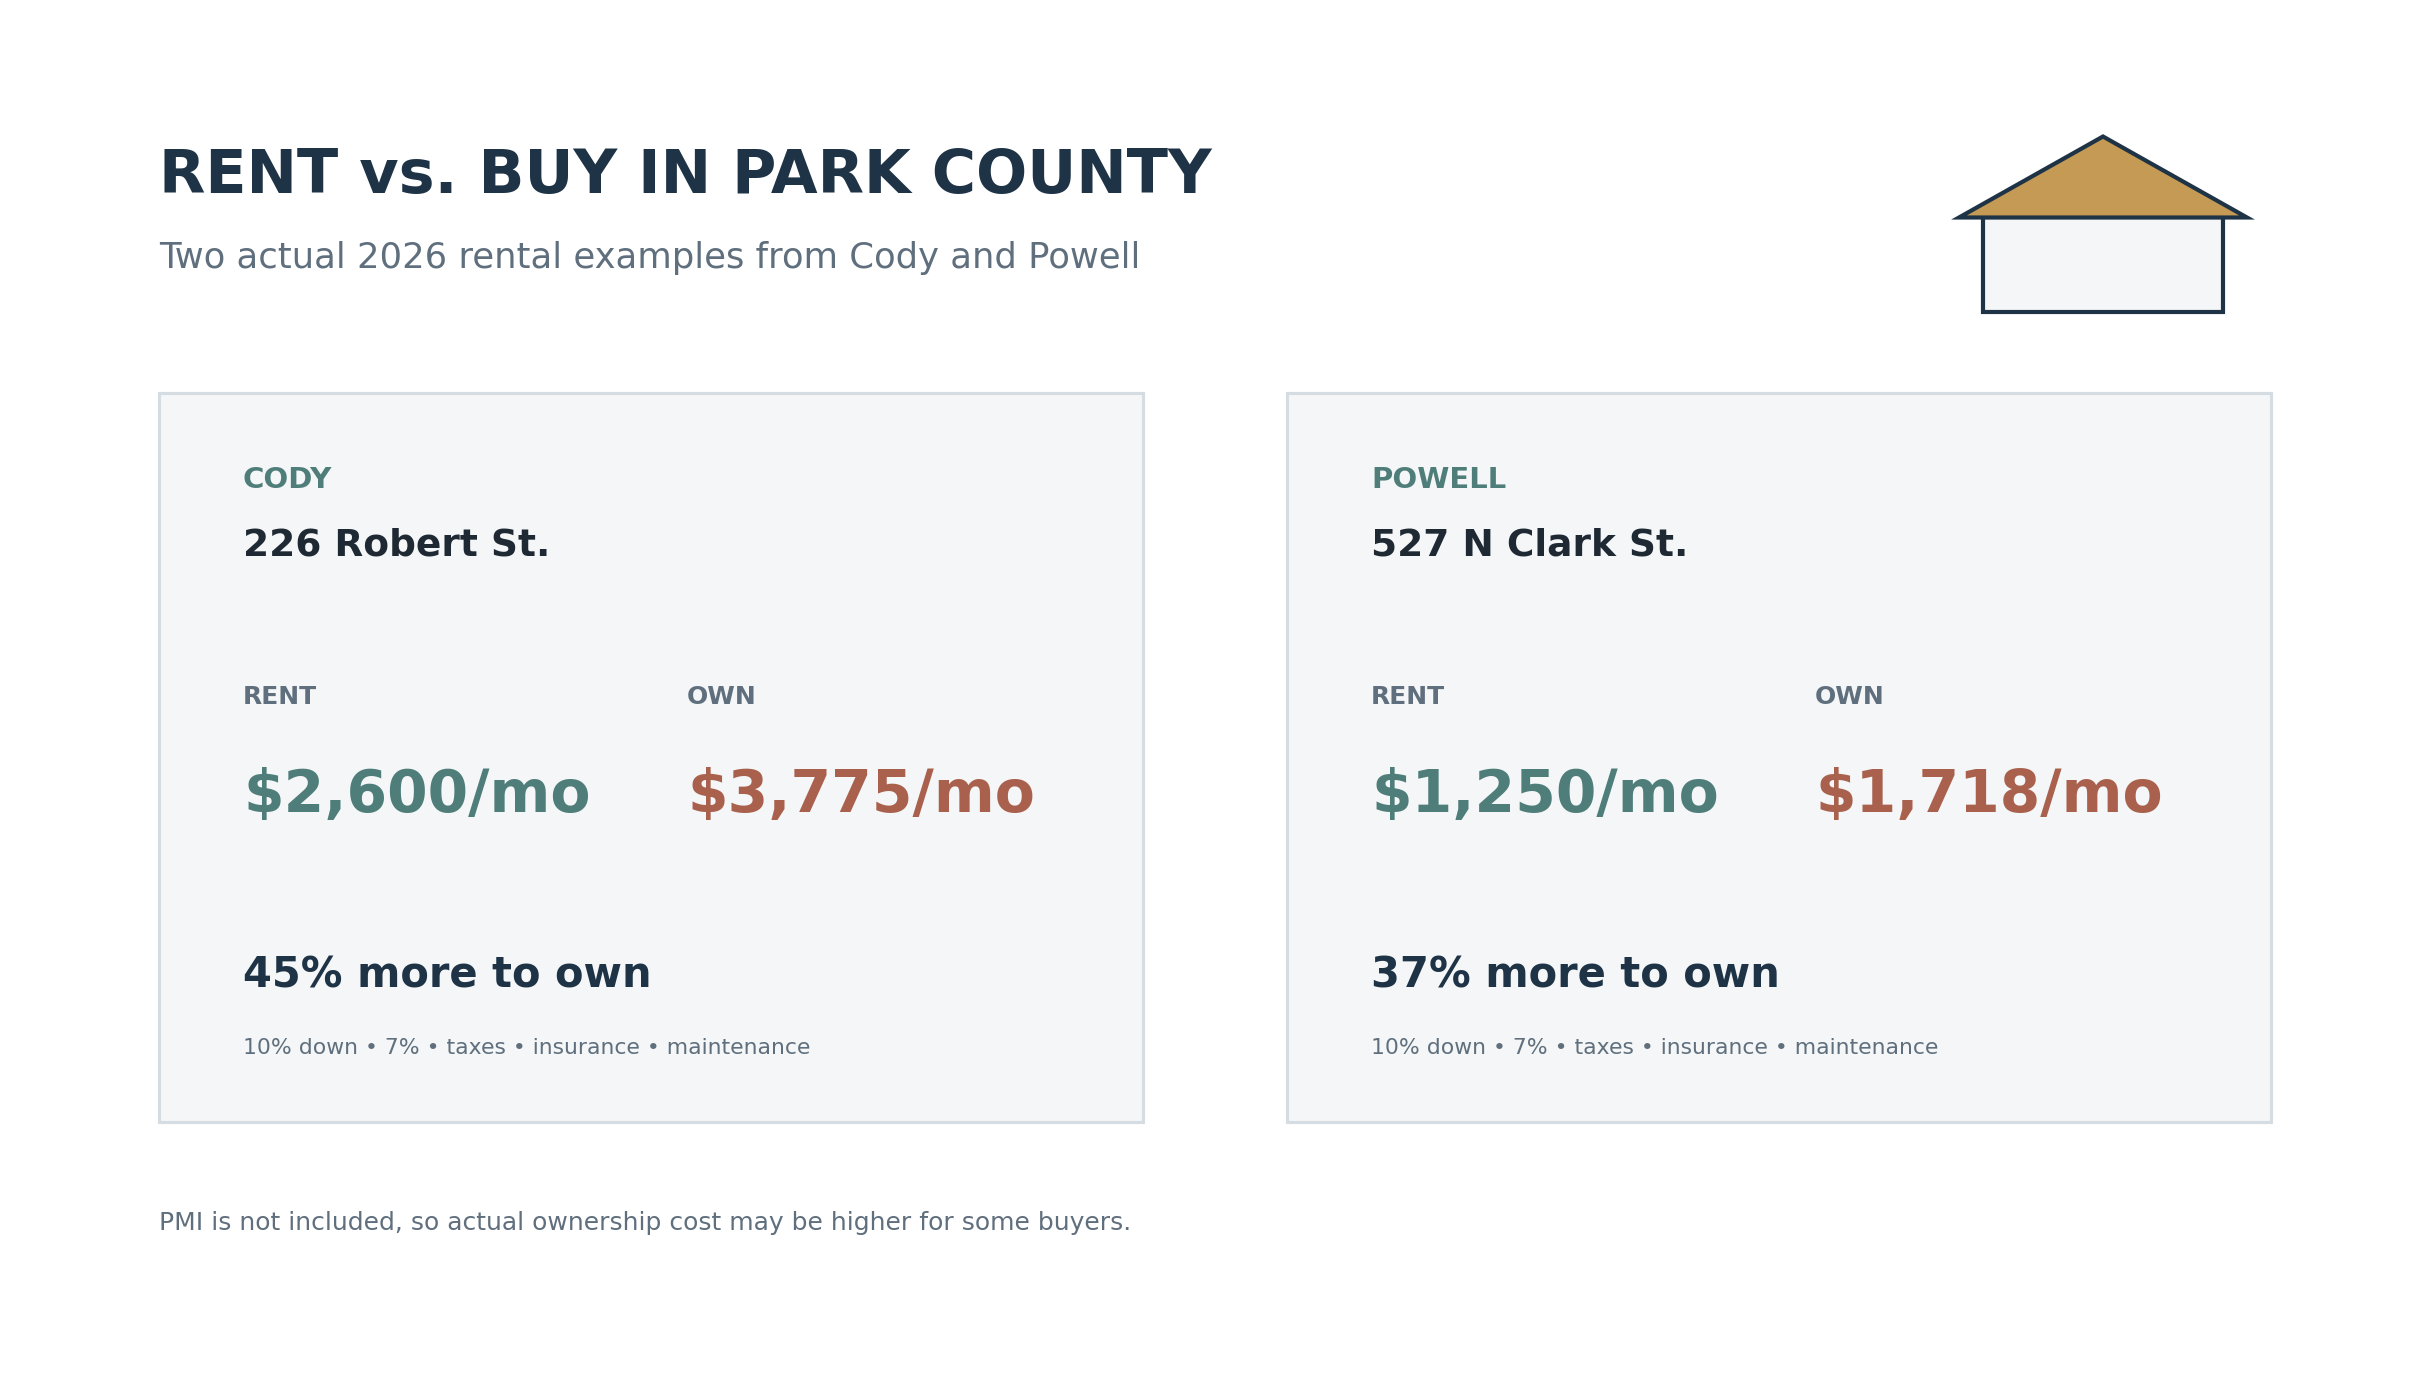
Figure 1. Actual Park County rental examples. PMI is excluded.
If you are deciding whether to rent or buy a home in Wyoming in 2026, the answer may surprise you. With mortgage rates near 7%, renting the exact same house can cost substantially less each month than buying it. That does not automatically make renting the better long-term financial decision. Homeowners build equity, may benefit from appreciation, get the freedom of using the property as they see fit, and eventually can own the property free and clear. But the old argument that “renting is throwing money away” skips an important first question: How much more does it cost to own the same house today?
Rather than compare a statewide average rent with a statewide average home price, this article uses actual homes marketed for rent by American West Realty & Management in Park County and compares each property’s rent with the estimated cost of buying that same property.
Nationally, renters already have a sizable monthly advantage
A September 16, 2026 Scotsman Guide article, citing Zillow research, reported that the average U.S. renter paid $1,066 less per month than the typical homebuyer in August. The article reported average rent of $1,948 versus a typical new-homeowner payment of $3,014 including taxes and insurance — a potential annual difference of $12,792. [1]
That national comparison is useful context, but it has a limitation: the average renter and average buyer may not be occupying comparable homes. A one-bedroom apartment should not be compared with a three-bedroom single-family purchase and treated as a perfect rent-versus-buy test.
A more useful question: What would it cost to rent a specific home instead of buying it?
Assumptions used in the Park County examples
To make the examples consistent and realistic, the calculations use the following assumptions:
- 10% down payment.
- 30-year fixed-rate mortgage.
- 7% interest rate.
- Actual property taxes supplied for each example.
- Estimated homeowners insurance based on the property example.
- Maintenance reserve included as a real cost of ownership.
- Utilities are excluded because both owners and renters typically pay them.
- PMI is excluded because the exact premium depends on the borrower and loan; this means the buyer calculations are actually conservative.
The 7% assumption is close to current market conditions: Freddie Mac reported an average 30-year fixed mortgage rate of 6.95% on September 17, 2026. [2]
A 10% down payment is also more realistic than assuming every buyer puts 20% down. If a buyer put down just 3% - 5%, as many do, the mortgage numbers would be even higher. The National Association of REALTORS® reported a 10% median down payment for first-time buyers in its 2025 Profile of Home Buyers and Sellers. [3]
Because both examples assume less than 20% down, many conventional borrowers would also pay private mortgage insurance. The Consumer Financial Protection Bureau notes that mortgage insurance is typically required when borrowers put less than 20% down. [4]
Example 1: 226 Robert St., Cody
American West Realty & Management is marketing 226 Robert St. in Cody at a total monthly price of $2,600. The property is a modern, above-average home with 3-bedrooms, 2-baths, 1,708-square-foot. [5]
For this comparison, we use a $506,000 tax-assessed value (lower than market value).
226 Robert St. | Rent | Buy |
Purchase price | — | $506,000 |
10% down payment | — | $50,600 |
Mortgage amount | — | $455,400 |
Principal & interest @ 7% | — | $3,030 |
Property taxes | — | $295 |
Homeowners insurance | — | $150 |
Maintenance allowance | — | $300 |
Total monthly housing cost | $2,600 | $3,775 |
Monthly difference | — | +$1,175 |
Annual cash-flow difference | — | +$14,097 |
Result: Buying requires about $1,175 more per month, or approximately 45% more monthly cash than renting.
Maintenance sensitivity: The $300 monthly maintenance figure above is the owner’s practical estimate. If we instead apply a standardized 1% annual maintenance reserve to the $506,000 value, the reserve becomes about $422/month and total ownership cost rises to about $3,896/month — essentially 50% more than the $2,600 rent. |
Example 2: 527 N Clark St., Powell
527 N Clark St. was marketed by American West Realty & Management at a total monthly price of $1,250. [6][7]
For the purchase side, we use a current estimated market value of $220,000, annual property taxes of $1,405 and annual homeowners insurance of $1,200.
527 N Clark St. | Rent | Buy |
Purchase price | — | $220,000 |
10% down payment | — | $22,000 |
Mortgage amount | — | $198,000 |
Principal & interest @ 7% | — | $1,317 |
Property taxes | — | $117 |
Homeowners insurance | — | $100 |
Maintenance reserve (1%/yr) | — | $183 |
Total monthly housing cost | $1,250 | $1,718 |
Monthly difference | — | +$468 |
Annual cash-flow difference | — | +$5,613 |
Result: Buying costs about $468 more per month, or approximately 37% more than renting the same house.
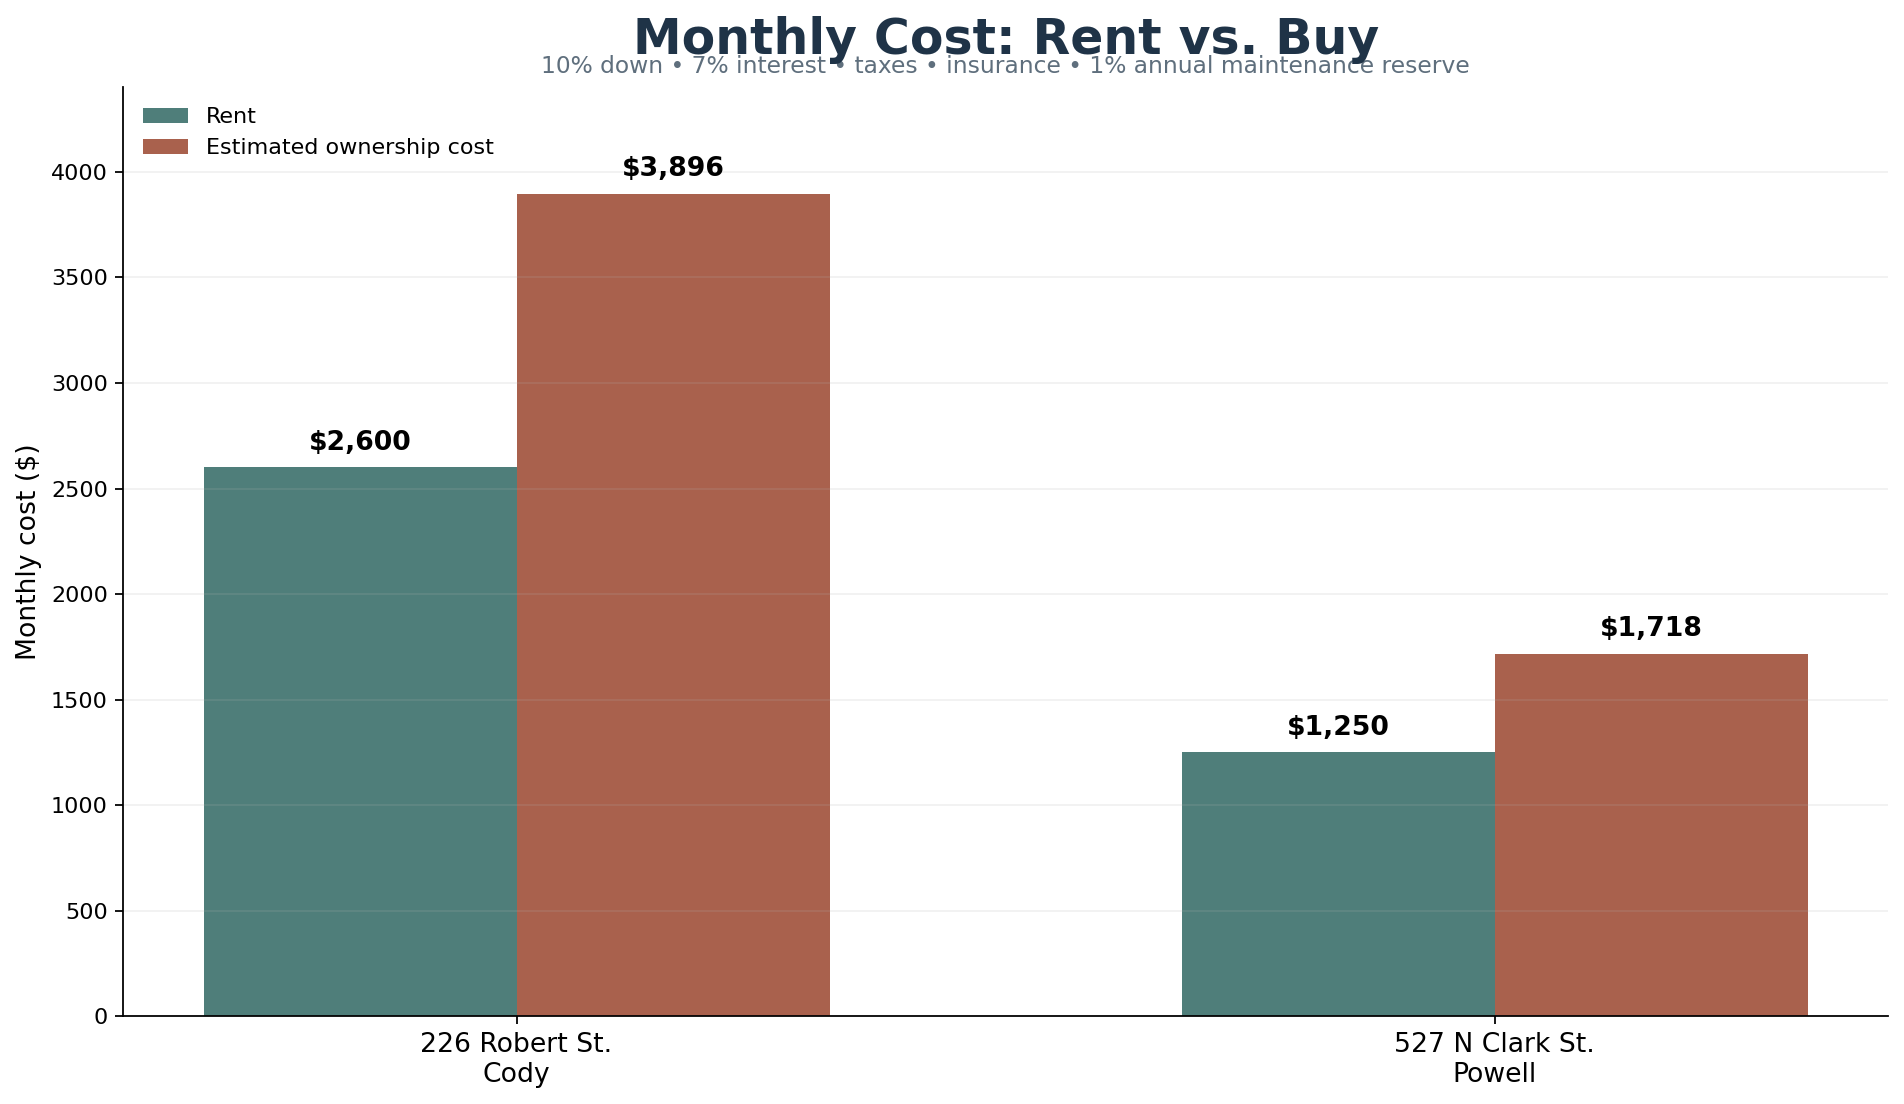
Figure 2. Apples-to-apples monthly comparison using a 1% annual maintenance reserve for both properties. PMI is excluded.
What the two Park County examples show
Property | Rent | Standardized ownership cost | Monthly premium | Premium to own |
226 Robert St., Cody | $2,600 | $3,897 | +$1,296 | +50% |
527 N Clark St., Powell | $1,250 | $1,718 | +$468 | +37% |
The examples do not prove that renting is always cheaper everywhere in Wyoming. They demonstrate why a same-property comparison is more useful than statewide averages. The relationship between a home’s purchase value and its achievable rent can vary dramatically from property to property.
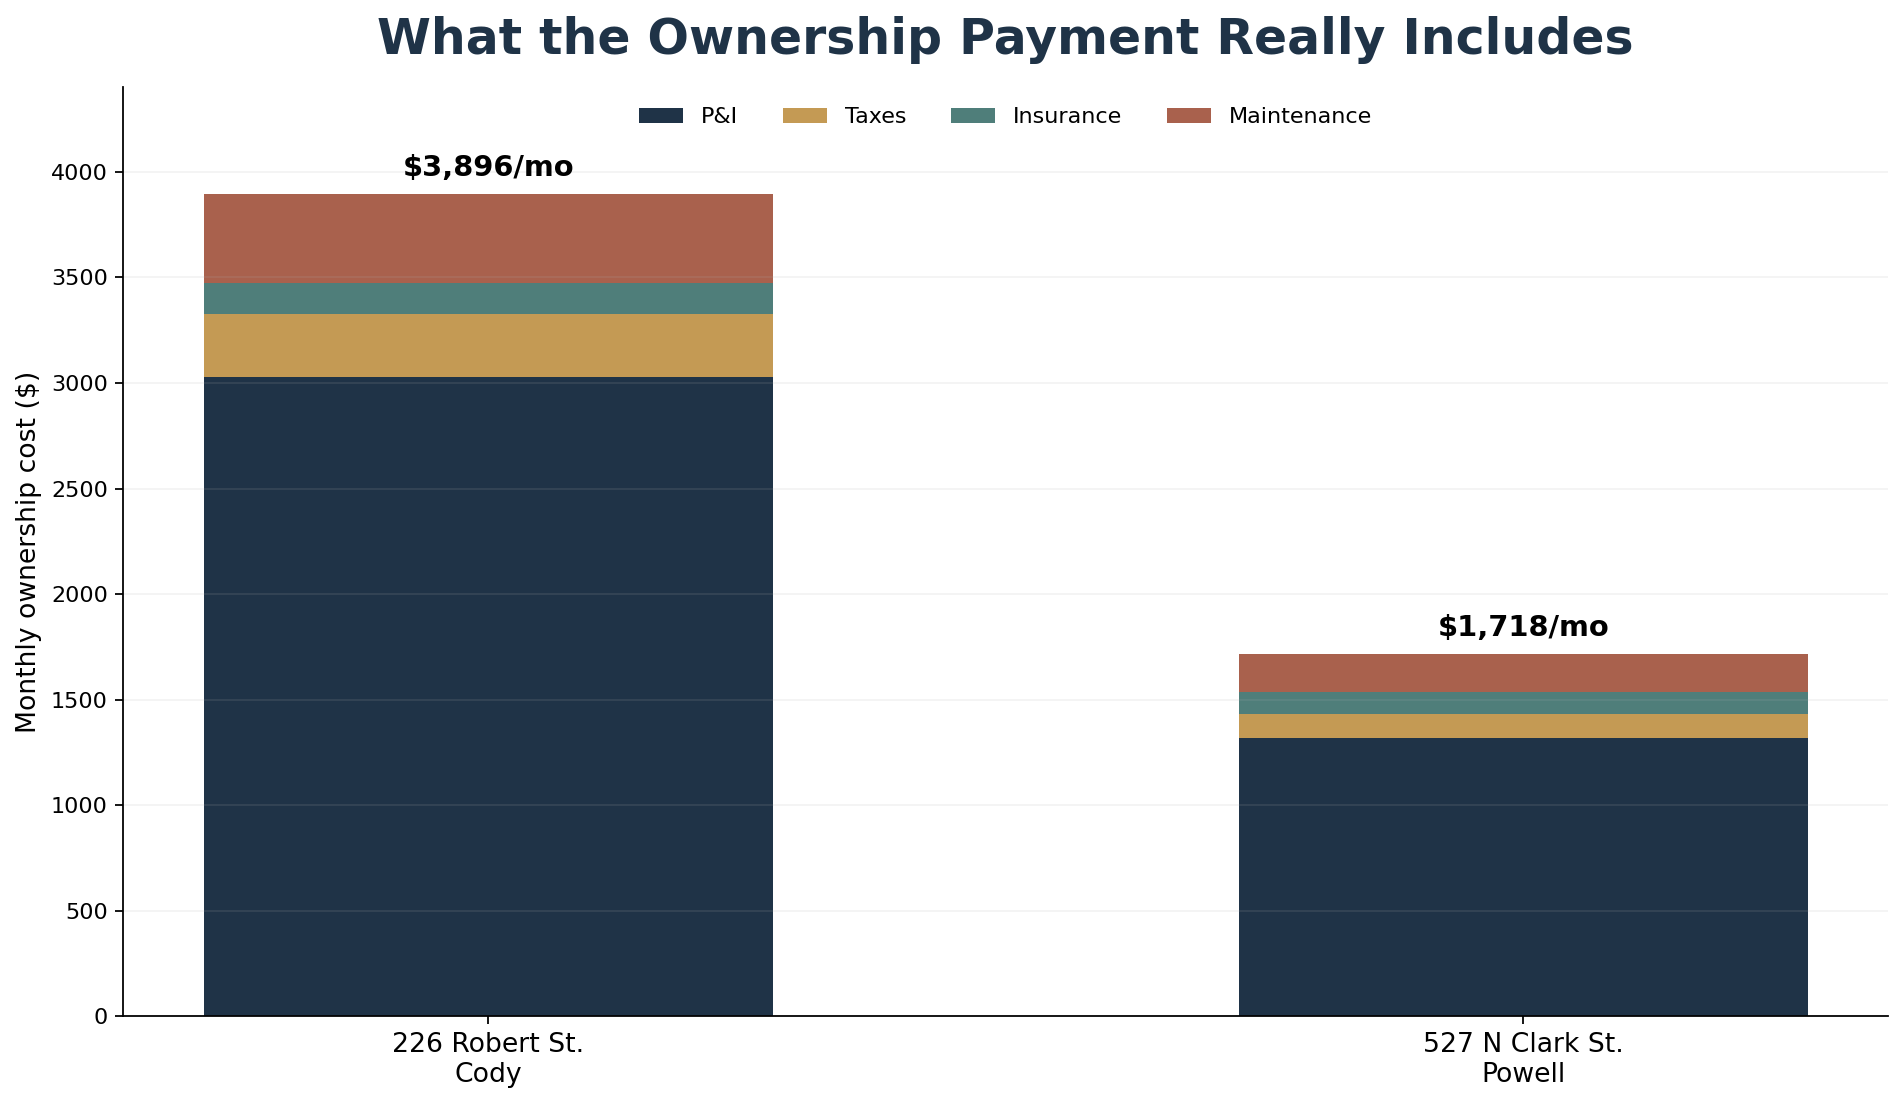
Figure 3. Ownership cost includes principal and interest, taxes, insurance and a 1% annual maintenance reserve. PMI is not included.
But part of the mortgage payment builds equity
This is the strongest argument against comparing rent with the full mortgage payment and stopping there. A renter’s payment is an expense that they never get back. A homeowner’s principal-and-interest payment contains both interest and principal, and the principal portion reduces the loan balance, referred to as equity.
On the Cody example, the buyer would pay down about $4,626 of principal during the first 12 months — roughly $385 per month. On the Powell example, first-year principal reduction is about $2,011, or $168 per month.
That equity creation matters, but it does not eliminate the cash-flow gap. Using the standardized maintenance reserve, Cody still requires roughly $911 more per month after subtracting first-year principal creation from the ownership cash outflow. Powell still requires roughly $300 more per month on the same basis.
The buyer also needs much more cash upfront
Monthly cost is only one part of the comparison. With 10% down, the Cody buyer needs $50,600 for the down payment; the Powell buyer needs $22,000. Closing costs are additional. The CFPB says closing costs typically run about 2% to 5% of the purchase price, excluding the down payment. [8]
Property | 10% down | 2%–5% closing costs | Approx. cash before moving/repairs |
226 Robert St., Cody | $50,600 | $10,120–$25,300 | $60,720–$75,900 |
527 N Clark St., Powell | $22,000 | $4,400–$11,000 | $26,400–$33,000 |
The renter retains most of that capital. Whether that becomes a financial advantage depends on what the renter does with the money: spend it, hold it in cash, pay down debt or invest it elsewhere.
What about appreciation?
Appreciation can materially improve the long-term ownership outcome. If a home rises in value while the mortgage balance falls, the owner can build wealth from both directions. But appreciation is not guaranteed, and transaction costs make short ownership periods particularly risky. A rent-versus-buy decision should therefore be evaluated over the time the household realistically expects to remain in the home — not by assuming a guaranteed annual increase in value.
Maintenance is a real cost, even when it is irregular
Maintenance is one of the costs most often omitted from simple mortgage calculators. Homeowners eventually pay for roofs, furnaces, water heaters, appliances, plumbing, sewer lines, exterior maintenance, flooring, landscaping and other repairs. Those expenses do not arrive evenly each month, which is precisely why a reserve is useful for planning.
A renter still pays indirectly because landlords must recover operating expenses through rent. The difference is that the renter generally transfers the timing and capital-repair risk to the property owner.
PMI could widen the gap further
The examples intentionally exclude PMI because the exact premium depends on the borrower and loan. But with only 10% down, many conventional borrowers would pay it. CFPB guidance says mortgage insurance is typically required below 20% down and increases the cost of the loan. [4]
In other words, these examples should not be read as worst-case ownership costs. For a buyer who pays PMI, the actual monthly difference could be larger.
When buying may still make more sense
- You expect to remain in the property for many years.
- The purchase price is low relative to the rent the property would command.
- You have a larger down payment or obtain a lower interest rate.
- You value long-term stability and control over the property.
- You are comfortable with repair and maintenance risk.
- You want the forced-savings effect of principal paydown.
- You believe the property is a sound long-term asset without relying on aggressive appreciation assumptions.
When renting may make more sense
- The rent is substantially below the all-in cost of owning the same home.
- You expect to relocate within a few years.
- A down payment and closing costs would consume too much of your available cash.
- You value flexibility or want to avoid major repair risk.
- You have a productive use for the monthly savings or the cash that would otherwise be tied up in the home.
A better way to compare rent versus buy
Do not start with “average Wyoming rent” and “average Wyoming home price.” Start with the actual home you would occupy.
1. Determine realistic market rent. What would this specific house actually rent for today?
2. Determine realistic purchase value. Use the contract price, recent comparable sales, an appraisal or another defensible current value.
3. Calculate financing. Use the down payment and rate you realistically expect — not an automatic 20% down assumption.
4. Add ownership costs. Taxes, insurance, PMI, HOA fees and a maintenance reserve belong in the comparison.
5. Then consider wealth creation. Estimate principal reduction, possible appreciation, the opportunity cost of the down payment and how long you expect to own the home.
So, is it cheaper to buy or rent in Wyoming in 2026?
American West Realty and Management oversees 300 residential rentals in Park County. In every instance, it is significantly cheaper to rent than to buy.
That local result is consistent with the broader national trend highlighted by Scotsman Guide, which reported a $1,066 monthly renter advantage nationally in August 2026 based on Zillow data. [1]
But lower monthly cost does not automatically mean you will end up better in the long run. The owner is paying more each month, but they are also building equity over time. The financial outcome depends on the property, the loan, the holding period, and what each household does with the money.
If you were to rent a house and it cost $1,000 less than buying the same house, you could set that additional money aside for three years and have a nice downpayment for a home when the market is more favorable. If you spend the money instead of saving, you may eliminate any advantage.
Want to run the numbers on a Park County property?
Whether you are deciding to rent, buy, sell or hold an investment property, start with realistic local rent and ownership numbers. American West Realty & Management can help buyers, renters, and investors evaluate current market rent and local property-management considerations in Cody, Powell and the surrounding Park County market.
Methodology and disclosure
The Park County examples use actual rental properties marketed by American West Realty & Management. Rental figures reflect the total monthly advertised price for the examples described above. The Cody purchase comparison uses a $506,000 tax-assessed value and owner-supplied tax, insurance and maintenance assumptions. The Powell comparison uses a $220,000 estimated market value, $1,405 annual property taxes and $1,200 annual insurance.
Mortgage calculations assume a 30-year fixed loan, 10% down and 7% interest. The standardized comparison uses a planning reserve equal to 1% of property value per year for maintenance. PMI is excluded because the amount is borrower-specific. Actual rates, taxes, insurance, repairs, closing costs and financing terms will vary.
This article is for general educational purposes and is not financial, tax, investment, appraisal or lending advice.
Source reference list
- Scotsman Guide — “Renters have a nearly $13,000 financial advantage over homeowners,” Sept. 16, 2026. https://www.scotsmanguide.com/news/renters-have-a-nearly-13000-financial-advantage-over-homeowners/
- Freddie Mac — Primary Mortgage Market Survey, Sept. 17, 2026 (30-year fixed average: 6.95%). https://www.freddiemac.com/pmms
- National Association of REALTORS® — 2025 Profile of Home Buyers and Sellers (first-time buyer median down payment: 10%). https://www.nar.realtor/news/real-estate-news/nar-2025-profile-of-home-buyers-sellers-reveals-market-extremes
- Consumer Financial Protection Bureau — Mortgage insurance guidance. https://www.consumerfinance.gov/ask-cfpb/what-is-mortgage-insurance-and-how-does-it-work-en-1953/
- American West Realty & Management / ShowMojo — 226 Robert St., Cody rental listing. https://showmojo.com/l/f91b087023/226-robert-st-cody-wy-82414
- Redfin — 527 N Clark St., Powell rental listing (American West/ShowMojo syndication). https://www.redfin.com/WY/Powell/527-N-Clark-St-82435/home/109332744
- Realtor.com — 527 N Clark St., Powell rental history showing July 2026 ShowMojo listing at $1,250. https://www.realtor.com/rentals/details/527-N-Clark-St_Powell_WY_82435_M89674-98086
- Consumer Financial Protection Bureau — Typical closing-cost range of 2% to 5% of purchase price. https://www.consumerfinance.gov/owning-a-home/prepare/figure-out-how-much-you-want-to-spend/
- Local property figures — American West Realty & Management / owner-provided Park County market, tax, insurance and maintenance data used for the property-specific examples.
#WyomingRealEstate #RentVsBuy #CodyWY #PowellWY #ParkCountyWY #WyomingHomes #HomeBuying #PropertyManagement #RealEstateInvesting